

November 9-10
|
LONDON
|
November 9-10 | LONDON |

Beauty Independent’s Dealmaker Summit is widely recognized as the premier sector-specific professional event for leaders involved in fund raising, capital strategy and M&A in beauty and wellness.
Renowned for its best-in-class content, the Dealmaker Summit features an expertly crafted agenda focused on topics relevant to beauty and wellness dealmakers, carefully curated panels that provide relevant yet diverse perspectives, and original research and insights presented by Beauty Independent’s Editorial team.
Join a diverse group of the most influential dealmakers active in the space, including strategics, private equity, venture capital, family offices, angel investors, incubators, investment bankers, as well as founders and CEOs of high growth brands for two-days of peer-level thought leadership and networking.
Summit
Agenda
I.INVESTMENT STRATEGY
-
Today’s deal climate is a market without a strong buyer. Outside of L'Oréal, every major strategic acquirer is navigating its own version of distress: restructuring, debt reduction, or the fallout of a collapsed mega-merger. Early capital is flowing, but the backlog of exit-ready assets is building against a buyer universe that is thinner and more cautious than any in recent memory. This session asks what happens to the brands that cannot wait for the recovery, and what a realistic path to exit actually looks like in today's market.
-
When Ulta Beauty acquired Space NK in July 2025, it surpassed Sephora in UK scale overnight and made a direct competitive play in one of the world's most discerning beauty markets. Space NK had posted four consecutive years of at least 30% annual sales growth and a consumer base growing fastest among shoppers under 25. The deal made sense—the harder work starts after the ink dries. This edition of Doing the Deal examines what made the transaction work, where Ulta’s ambitions lay for the future of SpaceNK, and what retailer-to-retailer M&A tells us about where beauty is headed next.
II.RETAIL & DISTRIBUTION
-
The practitioner recommendation has become one of the last forms of consumer trust that genuinely converts—and in Europe, where regulatory standards are among the most stringent globally, that trust carries compounded weight. Europe captured $5.4 billion of the global medical aesthetics market in 2025, and the brands building through professional channels are arriving at the acquisition conversation with something most cannot demonstrate: loyalty that was earned, not bought. This session examines what it truly means to be clinic-first, and whether credibility is a moat or a ceiling.
-
Building a beauty brand and scaling one require completely different thinking. For UK and European brands, phase two comes down to critical sequencing: when to enter Amazon U.S., and how to navigate a European marketplace landscape where Amazon leads in eight out of ten markets and TikTok Shop's GMV is growing by triple digits. This session draws a clear line between brand building and performance optimization—and gets practical about where, when, and how to show up.
-
U.S. K-beauty sales hit $2.8 billion in early 2026, up 48% year-over-year. Europe is following fast. Yepoda achieved 120% profitable growth in 2024, crossing $100 million in 2025 and rolling out across Sephora Europe. The European K-beauty market is projected to reach $5 billion by 2035. This session examines what the wave looks like from a European vantage point, which brands and investors are best positioned to capture it, and whether Europe is building its own K-beauty infrastructure—or importing a trend someone else will own.
III.PRODUCT OPPORTUNITIES
-
Fragrance remains one of beauty's most coveted investment categories, but the easy money has been made. The mid-market is softening as the category bifurcates, and with the biggest strategic moves already locked up, the next wave of deals will demand sharper conviction. This panel examines what separates the houses built to last from the brands riding a trend—and what buyers, founders, and investors need to get right to win in a market that is simultaneously booming and becoming more brutally selective.
-
The skincare market has become smarter, more fragmented and far more demanding. Consumers are increasingly splitting between clinically driven, professional-grade solutions on one end and value-oriented, ingredient-focused brands on the other—forcing retail skincare brands to work harder to justify their positioning, pricing and relevance. As a result, acquirers are becoming more selective, prioritizing assets with clearly defensible market positions, clinical credibility, strong consumer resonance and strategic fit. In a market where there is no longer “one skincare category,” what types of brands are truly positioned to win—and trade?
-
Once dominated by mass players, haircare is now one of prestige beauty’s fastest-growing segments. But with new entrants crowding shelves and the pro salon channel still tough to crack, the category faces fresh challenges. This session separates the science-led category builders from the trend-chasers — and examines what it will actually take to sustain haircare's premium positioning through the next deal cycle.
-
Colour is not stalling—it is shifting. The lip category is saturating, and the consumer's next creative outlet is forming. A new generation of British brands is building directly into that shift, and a gap is forming at the top of the market as its defining brand navigates corporate instability. The question is who moves first: a strategic buyer ready for another bet on prestige colour, or a financial sponsor content to build quietly and wait for the recovery that makes the exit possible.
IV.MARKET OPPORTUNITIES
-
Wellness is the most overused word in beauty and the least well defined. Beauty Independent has spent years mapping what the category actually encompasses, and the picture is far more complex than the supplement shelf suggests. This session brings together the investors doing that disaggregation work in real time—sharing how they are underwriting the category, which segments have earned their conviction, and where the most misunderstood opportunity actually sits.
-
2026 is the year of peptides—searches exploded 550% in 2025 and a projected $300 billion market is taking shape. But functional mushrooms, NAD+, adaptogens, and women's health platforms are all building momentum alongside them. This session examines the most promising areas of wellness innovation, where early-stage capital is concentrating, and which of today's emerging bets are worth backing.
-
AI in beauty is projected to nearly double to $10.86 billion by 2030, and McKinsey estimates it could unlock up to $10 billion in additional sector value. The brands deploying it today are already pulling away from those still debating it. This session asks whether AI will ultimately invert the beauty business model entirely—and whether the disruption ahead will be as fundamental as DTC was a decade ago.
the greatest minds
of our generation
-

Josie Buck
PRINCIPAL, VENREX
-

Chris Bates
DIRECTOR, WILLIAM BLAIR
-

EMILY BULLMAN
INVESTOR, JAMJAR INVESTMENTS
-

Joshua Britton
PhD, Founder & CEO, Debut
-

Angelo Castello
CEO, FACE GYM
-

Lopo Champalimaud
CO-FOUNDER & MANAGING DIRECTOR, V3 VENTURES, VERLINVEST
-

Mia Collins
BUYING DIRECTOR, BEAUTY, HARRODS
-

Laurent Droin
PARTNER, FELIX CAPITAL
-

Meili Eubank
VP, GENERAL ATLANTIC
-
Olivier Garel
MANAGIGN PARTNER, UNILEVER VENTURES
-

Marianna Hariki
FOUNDING PARTNER & CEO, MYRA PARTNERS
-

Elliot Isaacs
FOUNDER, MEDIK8
-

Alice Ko
INVESTMENT PARTNER, JOYANCE VENTURES
-

Colette Laxton
CO-FOUNDER, THE INKEY LIST
-

Evan Koetsenruijter
DIRECTOR, ADVENT INTERNATIONAL
-

Akash Mehta
CO-FOUNDER & CEO, FABLE & MANE
-

EVAN MERALI
MANAGING DIRECTOR, RAYMOND JAMES
-

Margaret Mitchell
CHIEF COMMERCIAL OFFICER, SPACE NK
-

SANDRA NAIT-AMER
MANAGING DIRECTOR, ROTHSCHILD
-

Alexandre Pagliano
MANAGING DIRECTOR, M&A & CORPORATE INTELLIGENCE, L'ORÉAL
-

Joël Palix
BRAND EXPERT
-

Vasiliki Petrou
INDUSTRY EXPERT
-

Scott Potter
MANAGING PARTNER, SF EQUITY PARTNERS
-
Mandy Zhou
MANAGING DIRECTOR, BARCLAYS
THANK YOU TO OUR SPONSORS
THOUGHT LEADERSHIP SPONSORS
NETWORKING SPONSORS





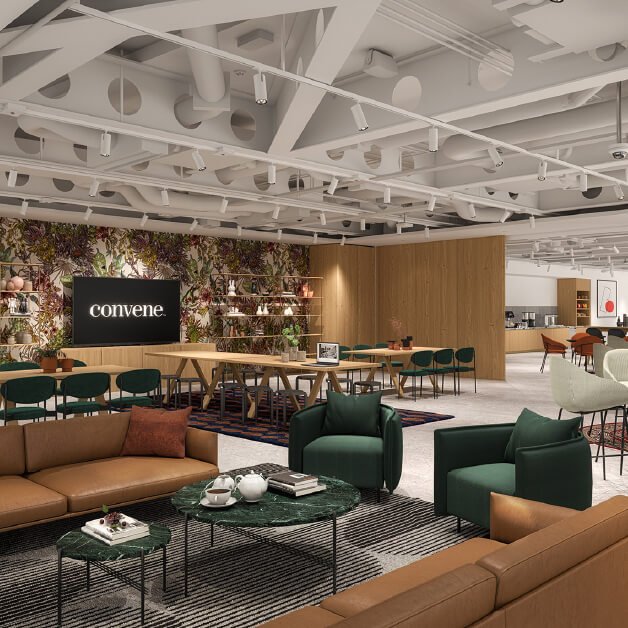
Convene London
22 Bishopsgate
City of London, London
November 9-10 | 8am to 5pm
The venue
Related
The Forever Brand Test: What Beauty Investors Really Want Now
Can Haircare Keep Its Big Mo?
Why Beauty M&A Isn’t Returning To Peak Form Anytime Soon
Where Industry Insiders See Skincare’s Biggest Business Potential Beyond Buzzy Ingredients
Beauty Brands Now Treat Amazon As A “Flagship, Not As An Outlet”
The Third Way: A New Era Of Beauty Dealmaking Emerges